Key Takeaways
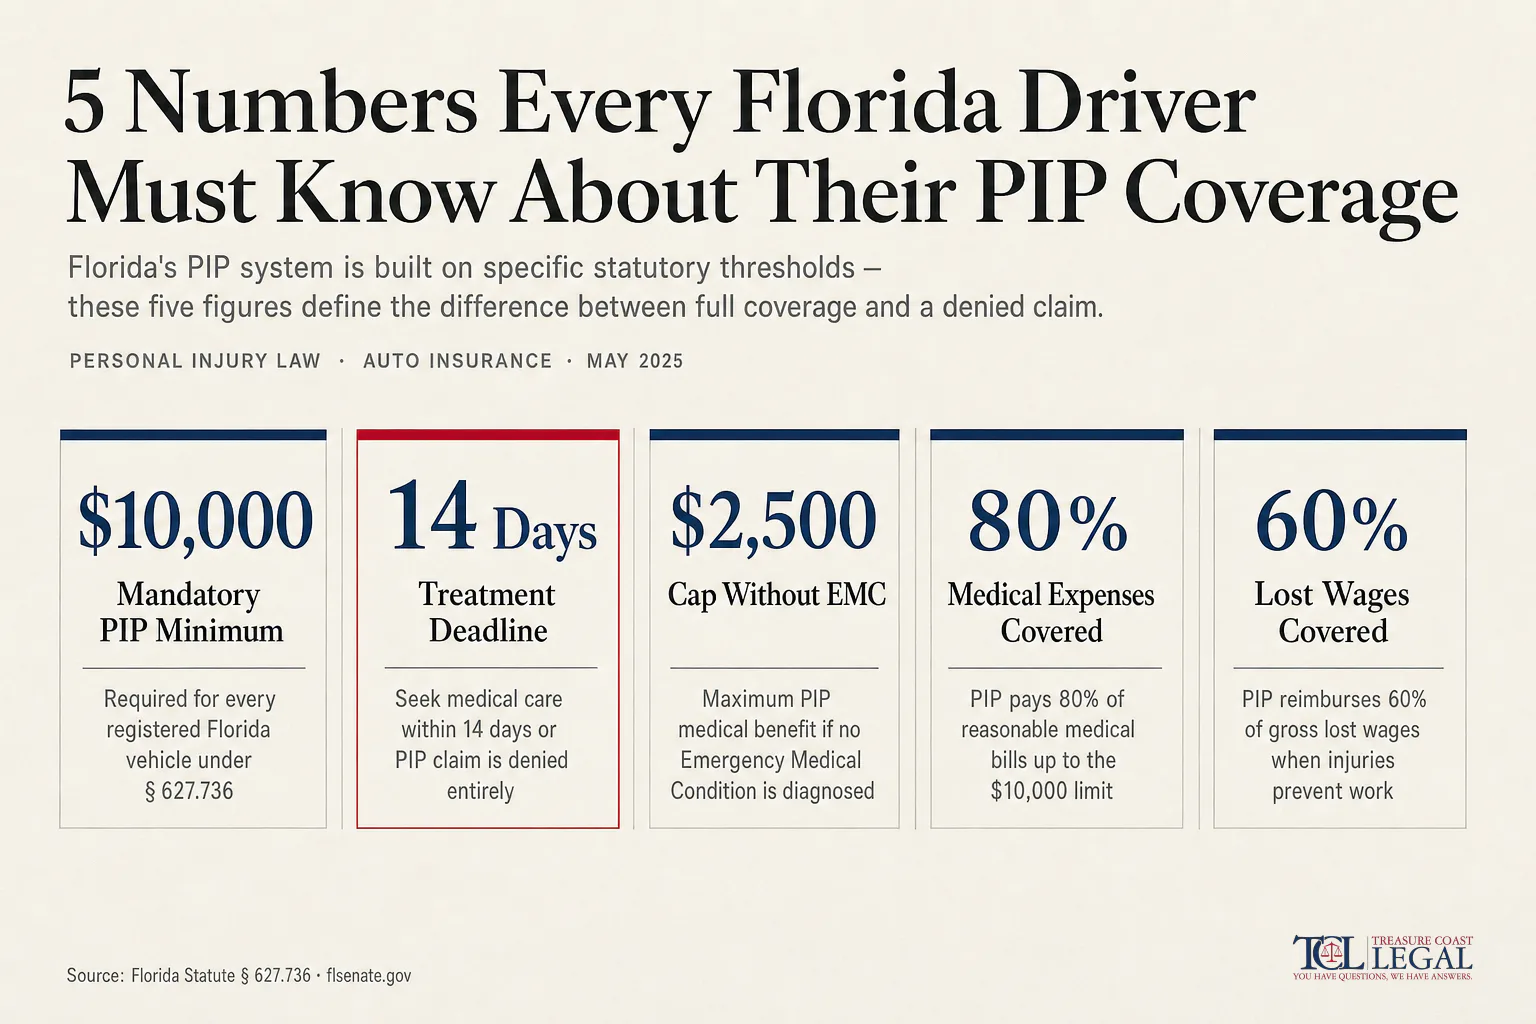
- Florida law requires every registered vehicle to carry a minimum of $10,000 in PIP coverage, and you cannot waive it.
- PIP pays 80% of reasonable medical expenses and 60% of lost wages, but only if you get treated within 14 days of the crash.
- Without an emergency medical condition diagnosis from a physician, your medical benefit drops to a $2,500 cap.
- PIP does not pay for property damage or pain and suffering.
- A denied PIP claim is often reversible. Insurers must pay or deny a clean claim within 30 days or owe interest.
*Written by Shaun Plymale, Founding Attorney.*
The Treasure Coast got its name from the 1715 Spanish treasure fleet that sank off what is now St. Lucie County. Florida drivers now carry a different kind of protection. So what is pip in insurance? Personal injury protection coverage is the coverage that pays your medical bills after an auto accident before anyone decides who was at fault. This article explains what PIP covers, what it does not, and what you must do in the first 14 days after a crash.
What PIP in Insurance Actually Means Under Florida's No-Fault Law
Florida is one of about 12 no-fault states, according to the Insurance Information Institute. Your own auto insurance policy pays your initial medical expenses regardless of who caused the accident. Every registered vehicle must carry a minimum of $10,000 in PIP coverage under Florida Statute § 627.736, per the Florida Bar consumer guide on automobile insurance. With about 250,037 people injured in Florida car accidents in 2023, this system gets victims covered fast. If you were hurt locally, our guide to personal injury claims in Fort Pierce walks through the process.
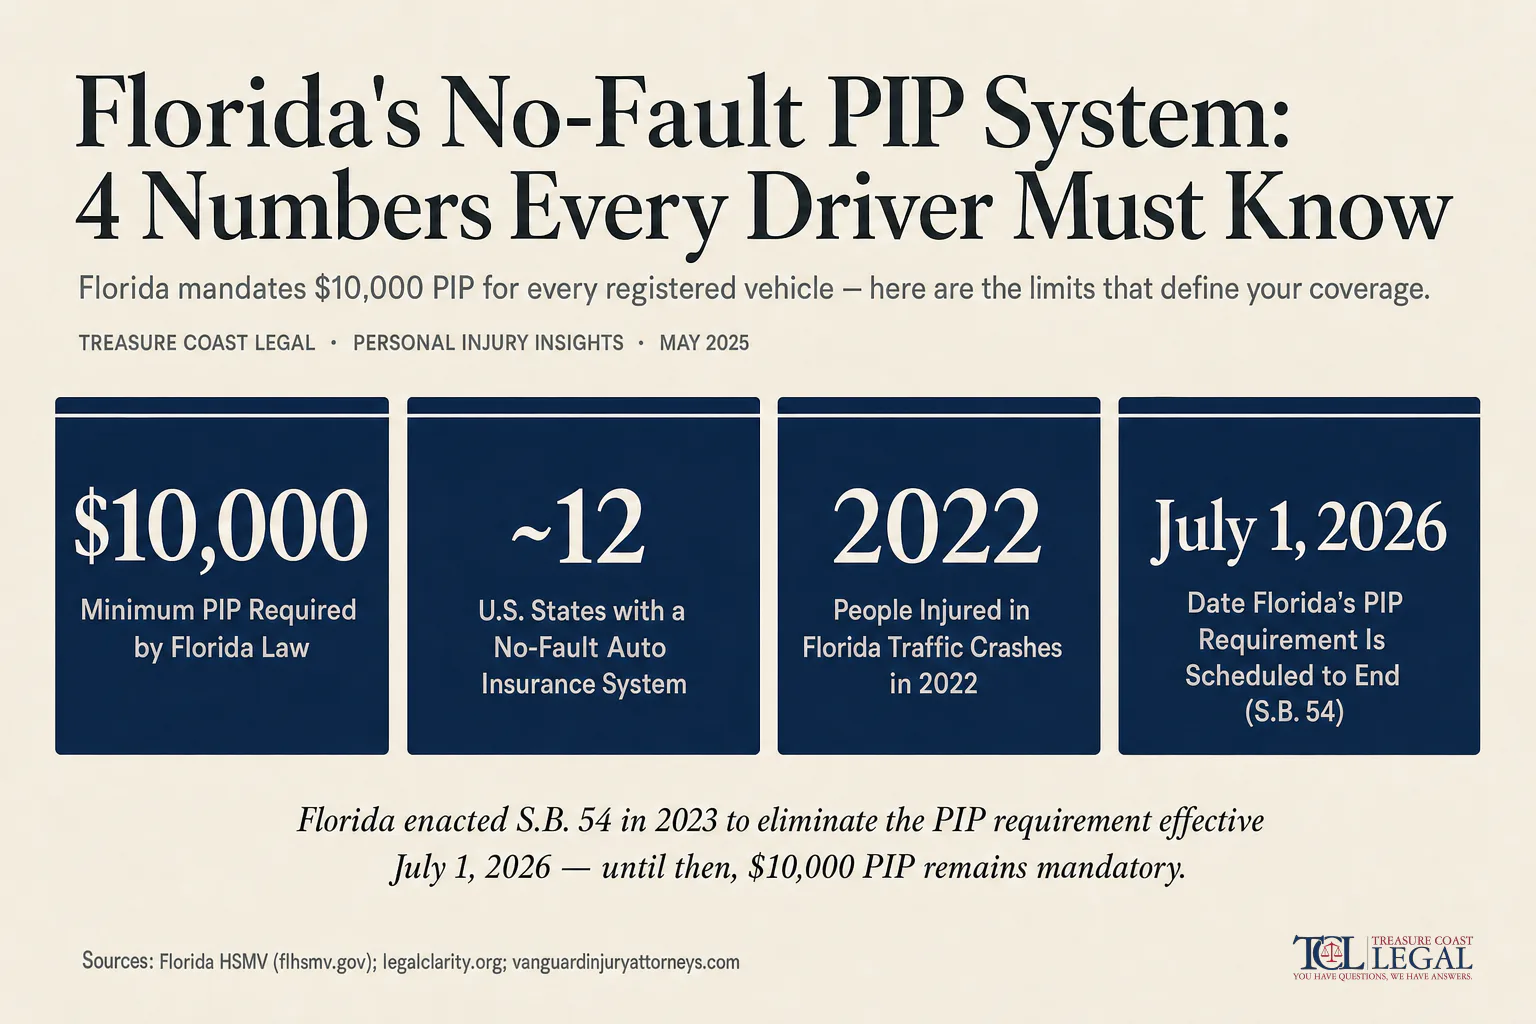
PIP Pays You, Not the Other Driver
Personal injury protection attaches to you and your household, not the at-fault party. Your own insurer pays your medical bills and a portion of your lost wages first. Never wait for the other driver to accept blame before seeking treatment after a car accident or automobile accident.
Who Is Covered Under Your Florida PIP Policy
Your PIP typically covers you, family members and relatives living in your household, passengers without their own PIP coverage, and you as a pedestrian or cyclist struck by a vehicle.
What Florida PIP Coverage Actually Pays For
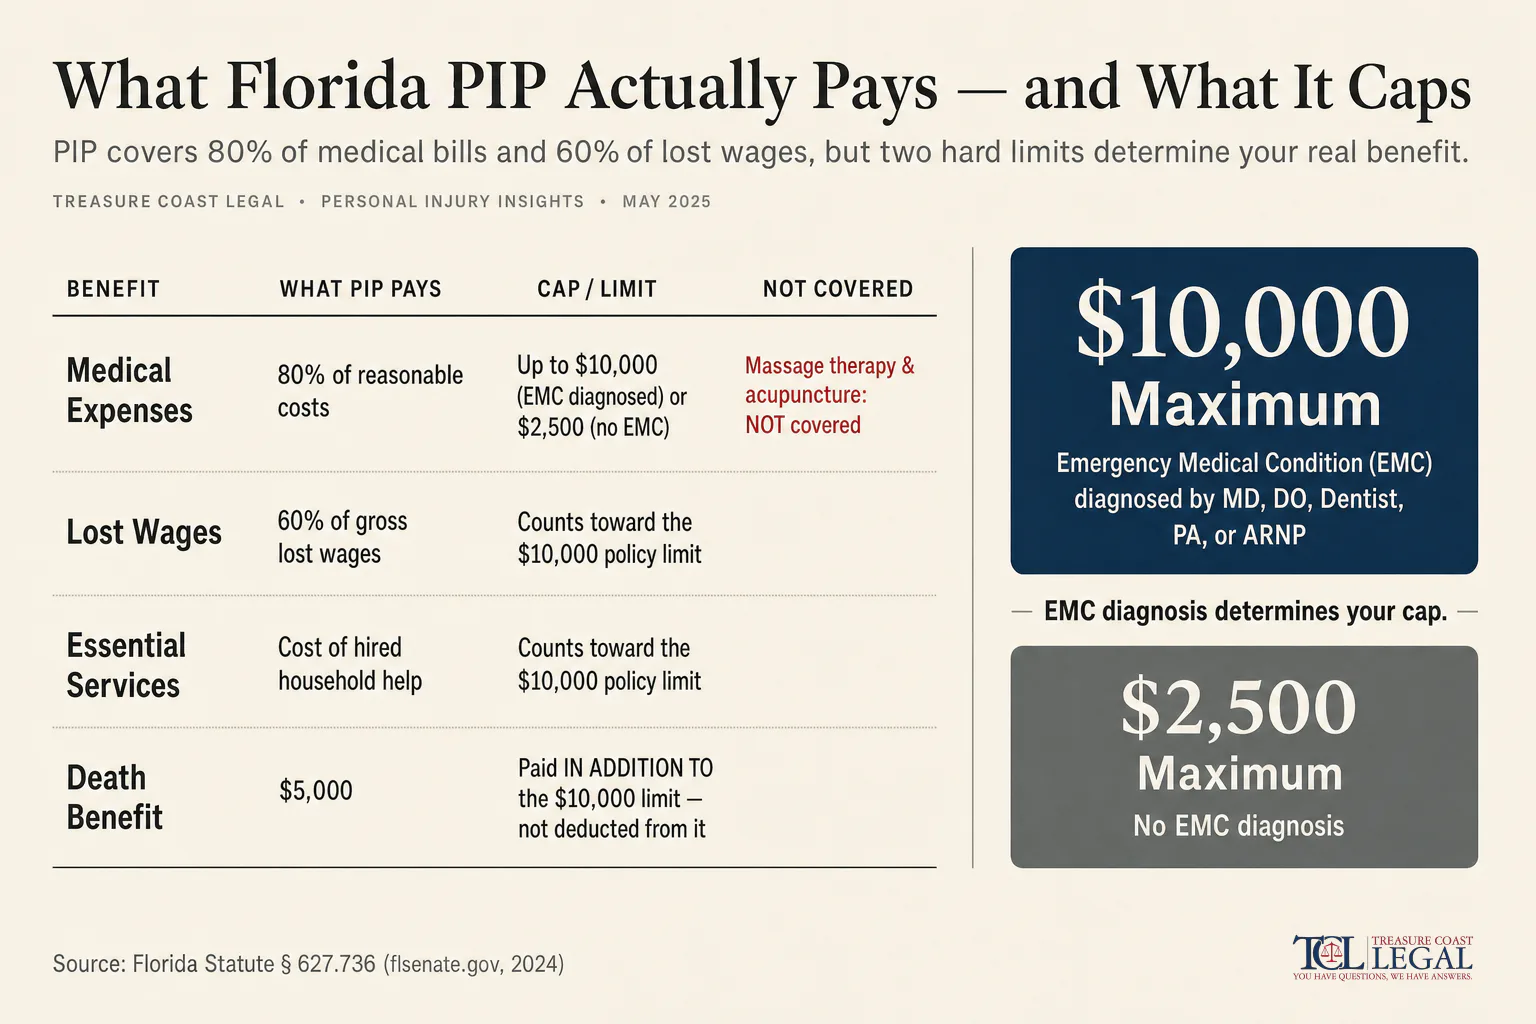
PIP covers 80% of reasonable and necessary medical expenses up to the $10,000 limit, but only if a licensed provider diagnoses an emergency medical condition (EMC) within 14 days, according to Florida Statute § 627.736. Without an EMC, that benefit drops to a $2,500 cap.
Lost Wages and Essential Services
PIP reimburses 60% of gross lost wages when injuries keep you from working, counting toward the same $10,000 limit. The pip coverage limits also include funeral expenses paid to the estate as part of the death benefit. Document missed workdays with payroll records and a physician's work-restriction note. PIP also pays for household help you can no longer perform, plus a $5,000 death benefit that covers funeral expenses paid to the estate.
What PIP Will Not Pay
Florida PIP excludes massage therapy and acupuncture entirely. Chiropractic care is eligible, but a chiropractor cannot certify an EMC, so seeing only a chiropractor can limit your benefit to $2,500.
What PIP Insurance Does Not Cover After a Florida Crash
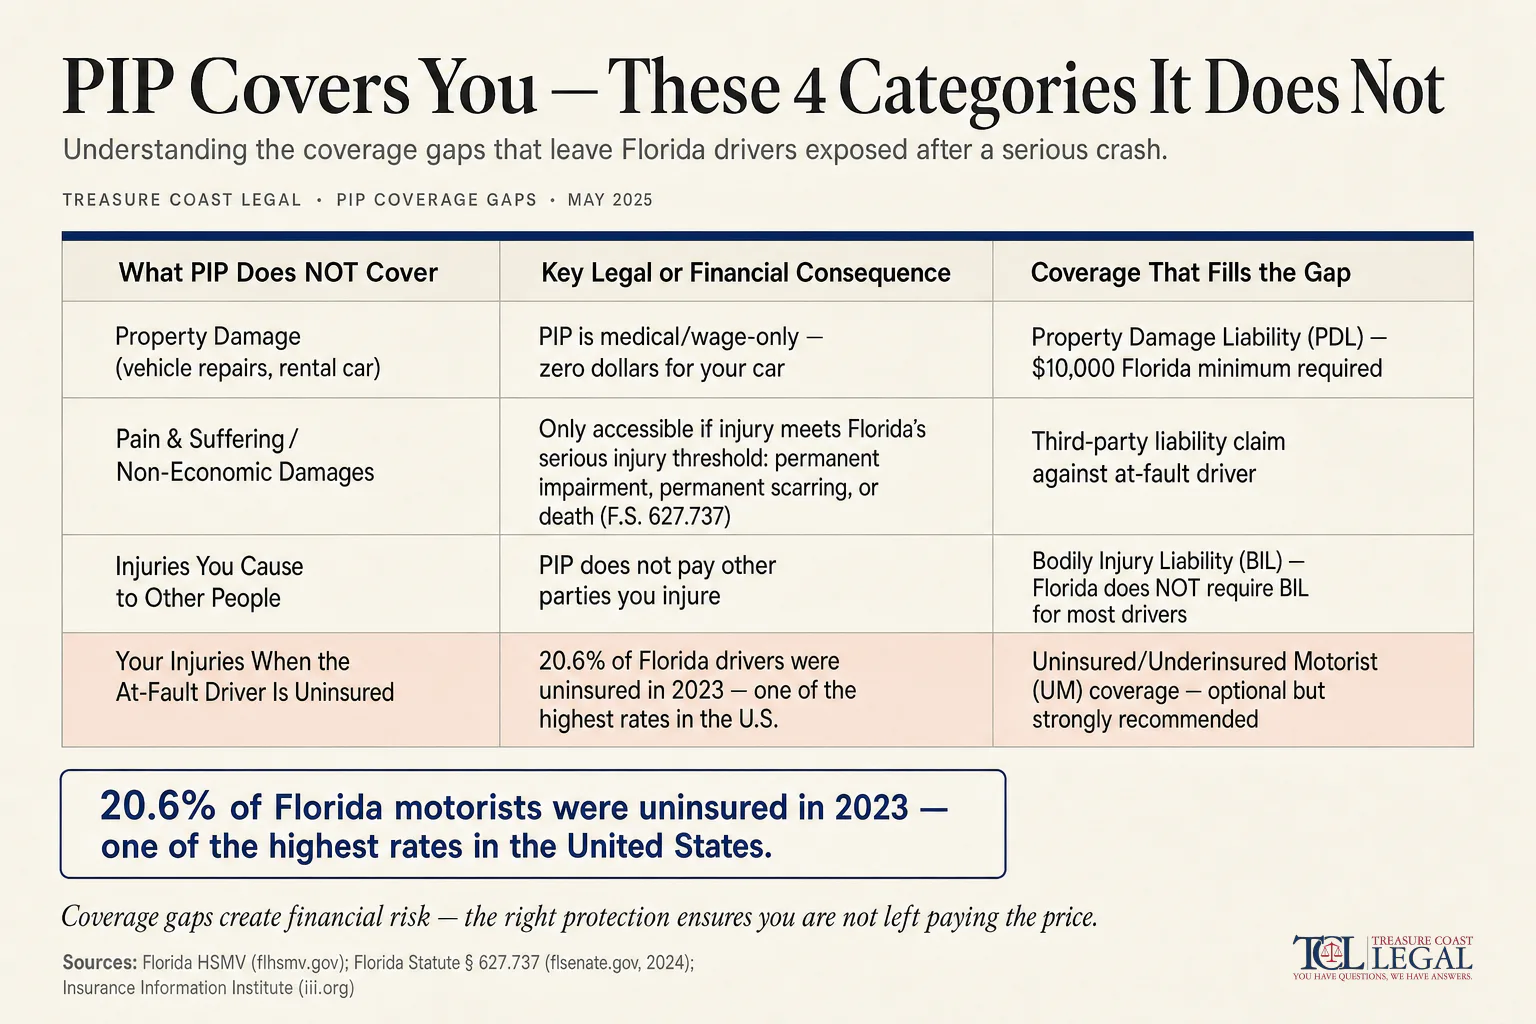
PIP is a medical and wage-replacement benefit only. It pays nothing toward vehicle repairs, rental cars, or other damages such as personal property. Florida requires separate property damage liability coverage of at least $10,000 for that. Call your insurer the same day to open a property damage claim, and ask about other auto insurance coverages that may apply.
Pain and Suffering Are Not PIP Benefits
PIP does not compensate for pain, suffering, or emotional distress, which are considered other damages beyond what fault insurance covers. To recover those, you must meet Florida's serious injury threshold, permanent injury, significant scarring or disfigurement, or death, under Florida Statute § 627.737. This is often the path for riders too, as our Treasure Coast motorcycle accident guide explains.
PIP vs. Bodily Injury Liability Coverage
PIP pays your own bills. Bodily injury coverage on the at-fault driver's auto insurance policy compensates you for damages PIP does not, like pain and suffering. Florida does not require bodily injury coverage, and the Insurance Research Council reports roughly 20.6% of Florida motorists were uninsured in 2023. Ask your agent whether you carry uninsured motorist coverage, which fills that gap.
How Florida's 14-Day Rule Controls Your Entire PIP Claim
Florida Statute § 627.736 requires initial medical treatment within 14 days of the accident to access PIP benefits at all. Miss this window and the insurer will typically deny the claim entirely. Schedule an evaluation within 48 hours of any crash.
The Emergency Medical Condition Requirement
Your full $10,000 unlocks only if a physician, osteopath, physician assistant, or ARNP diagnoses an EMC. Your first visit should be with a physician or ER, not a chiropractor.
How to File a PIP Claim
File with your own insurer. Notify your company promptly, submit the PIP application, authorize providers to bill directly, and cooperate with any examination under oath to keep the claims process on track. The insurer must pay or deny a clean claim within 30 days or the benefits accrue interest. A Port St. Lucie car accident lawyer can handle the filing.
How PIP Interacts With Your Health Insurance
In Florida, PIP is the primary payer for car crash-related medical bills. Your health insurance, whether private, Medicare, or Medicaid, pays only after PIP is exhausted. Tell every provider you have PIP coverage so they bill correctly.
When PIP Runs Out Before Treatment Ends
The $10,000 limit can be used up fast, an ER visit with imaging and a few therapy sessions can easily exceed it. Once your balance runs low, consult a personal injury attorney to preserve your recovery rights.
Med Pay vs. PIP
Medical payments coverage, or Med Pay, is an optional auto insurance coverage that can help pay medical expenses regardless of fault — including some or all of the remaining 20% of medical bills not covered by PIP — and is not subject to PIP's 14-day treatment rule. Whether and how Med Pay benefits are paid in addition to PIP depends on the specific limits and terms of your insurance policy. That small premium closes a real coverage gap.
Whether PIP Coverage Is Worth It and What Happens If You Waive It
Florida does not let you waive PIP. The $10,000 is mandatory. You can select a deductible up to $1,000 to lower your premium, but it applies to the full cost of care. A deductible makes sense only if you have a high deductible health plan or strong health coverage with low out-of-pocket costs.
Is $10,000 in PIP Enough
For minor accidents, $10,000 covers a lot. For anything involving surgery, imaging, or extended therapy, it is often gone within weeks. Florida's minimum is one of the lowest among no-fault states, New York requires $50,000, according to the New York Department of Financial Services. Drivers with assets to protect should consider their coverage options, such as Med Pay or higher health limits.
When Your PIP Claim Gets Denied and What to Do Next
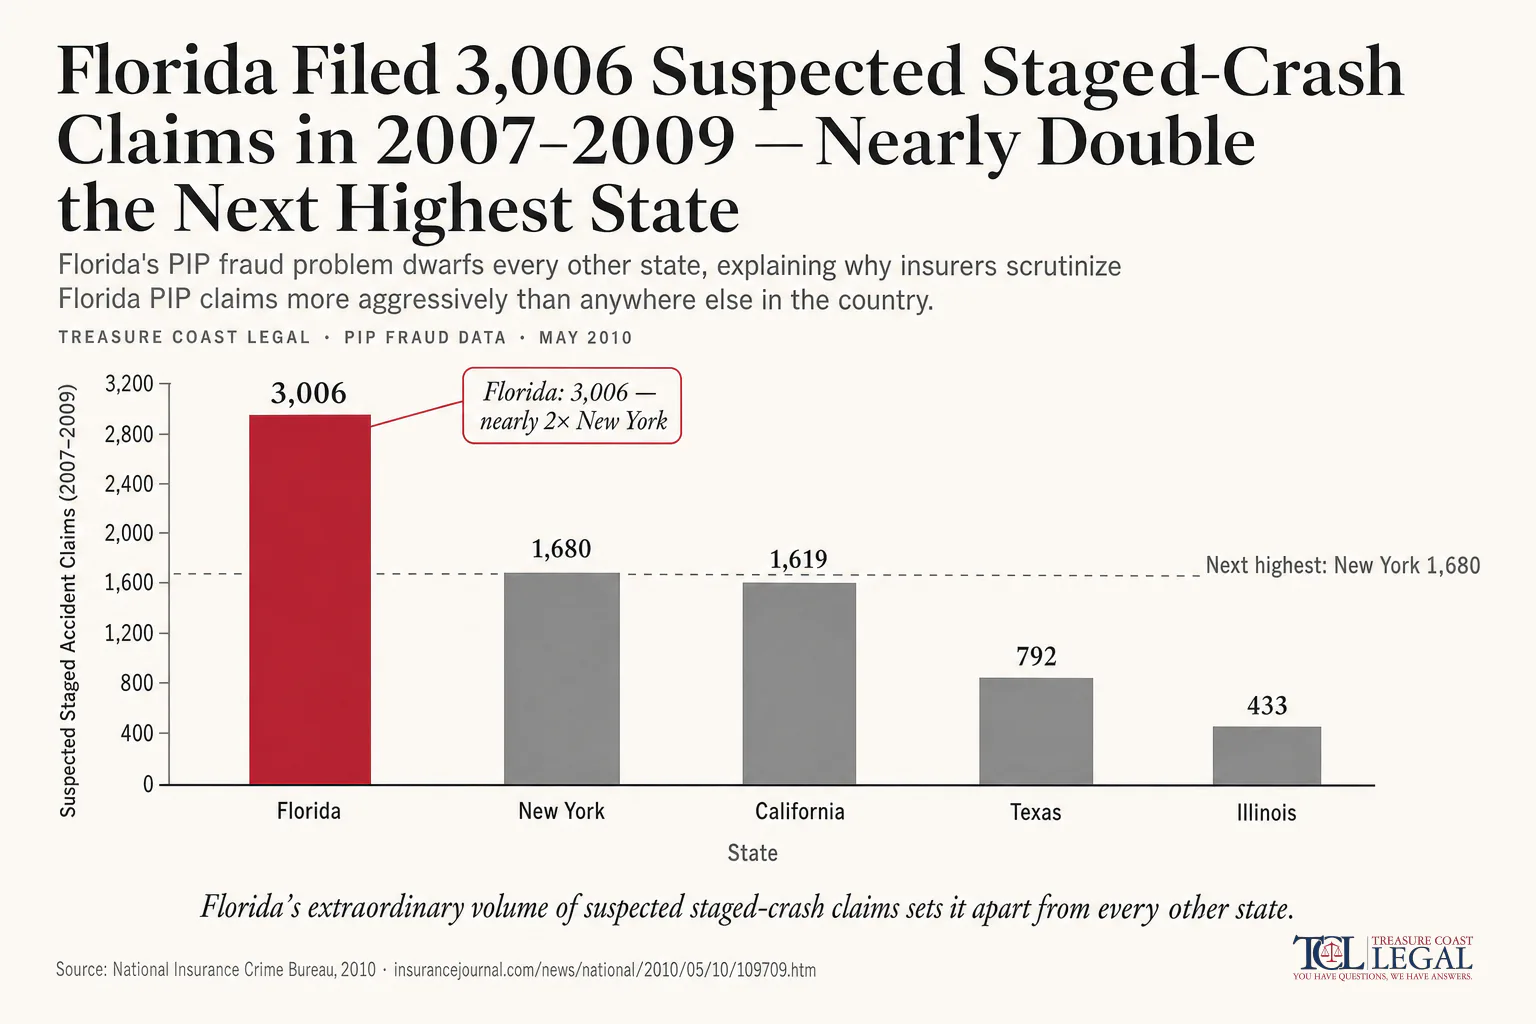
Insurers deny auto insurance claims for documented reasons, treatment sought after the 14-day window, no EMC diagnosis, treatment by a non-qualified provider, missing a required examination under oath, or a finding that care was not reasonable, related, and necessary. Fraud is also scrutinized heavily. Florida once led the nation in staged crashes, with 3,006 suspected staged-crash claims filed from 2007 to 2009, nearly double the 1,680 in New York, as reported by Insurance Journal citing the National Insurance Crime Bureau.
Your Right to Dispute a PIP Denial
Florida law gives you the right to challenge a wrongful denial. Insurance companies must send a written denial stating the statutory basis. An attorney can send a pre-suit demand under § 627.736 that often resolves the dispute without litigation, and a prevailing claimant may recover overdue benefits with interest.
Frequently Asked Questions About What Is PIP in Insurance
What does PIP do in insurance?
It pays 80% of necessary medical costs and 60% of lost income up to a combined $10,000 limit, regardless of fault, making personal injury protection pip insurance a key safeguard for Florida drivers.
Is PIP coverage worth it in Florida?
Florida law requires it. For drivers without robust car insurance coverage or with dependents, higher limits or a Med Pay add-on are generally worth it.
How does PIP pay out after a crash?
Providers usually bill your insurer directly after you sign a PIP assignment under your auto policy, and the insurer pays 80% of approved charges. For lost wages, you submit documentation and the insurer reimburses 60% of gross pay up to the limit.
Can I waive PIP coverage in Florida?
No. Florida Statute § 627.736 requires every registered vehicle owner to carry at least $10,000 in personal injury protection coverage. You can choose a deductible but cannot eliminate PIP.
What to Do Right Now If You Were Just in a Treasure Coast Crash
If you were injured in a crash anywhere in Martin or St. Lucie County, the 14-day clock started the moment of the crash. PIP is your first financial shield, but it carries strict deadlines, coverage limits, and denial traps. Our team at Treasure Coast Legal handles personal injury claims across the region on a contingency fee basis, so you owe nothing unless we recover for you, and we offer free consultations. Call 772-238-7755 or schedule your free consultation here before your window to act closes.
The information provided in this blog is for general informational and educational purposes only and is not intended as legal advice. Laws and legal outcomes vary based on specific facts and circumstances, and the information contained herein may not reflect the most current legal developments. You should not act or refrain from acting based on any information in this blog without first seeking legal advice from a qualified attorney licensed in your jurisdiction. This blog may be produced, in whole or in part, with the assistance of generative artificial intelligence tools and is reviewed by legal professionals before publication; however, no representations are made as to its accuracy, completeness, or applicability to any specific situation. Reading or interacting with this blog does not create an attorney-client relationship between you and the firm. An attorney-client relationship is formed only through a written agreement signed by both you and the firm. This blog may be considered attorney advertising under applicable laws and ethical rules. Prior results do not guarantee a similar outcome. The firm disclaims all liability for actions taken or not taken based on the content of this blog.
Shaun Plymale Founding Attorney Treasure Coast Legal